The Bank of Canada has raised interest rates, and the effect on real estate goes beyond the next mortgage payment.
It can change what buyers qualify for, how they negotiate, what sellers can realistically expect, and whether an investment still makes financial sense.
On October 28, the Bank increased its policy rate by a quarter of a percentage point to 2.50%. It also left the door open to further increases, with the next scheduled decision on December 9. (bankofcanada.ca; full statement text reproduced by BNN Bloomberg)
If you are considering a move in Greater Vancouver, this is a good time to revisit your numbers and your strategy.
Why raise rates when housing already feels expensive?
The Bank of Canada’s job is to control inflation across the economy. Its concern is that higher energy costs could spread into transportation, production, and everyday prices, making inflation harder to bring down.
The Bank now projects inflation averaging about 3% in 2027 before returning to its 2% target around the middle of 2028. That outlook could change, but it explains why the Bank has become more cautious about inflation. (bankofcanada.ca; full statement text reproduced by BNN Bloomberg)
At the same time, the economy is showing signs of weakness. October 30 data showed essentially no growth in August, with an early estimate suggesting a small contraction in September. (statcan.gc.ca)
That creates a difficult balance. Higher rates can help restrain inflation, but they also make borrowing more expensive for households and businesses.
For real estate, that means we should prepare for uncertainty rather than assume a predictable series of increases or decreases.
For buyers, purchasing power is the number to watch
Most buyers start with a price range. A lender starts with income, debt, qualification rules, and the cost of carrying the mortgage.
When mortgage rates rise, some buyers may qualify for less, even though their income and down payment have not changed.
My view is that this can shift demand between price ranges and property types. A buyer considering a detached home may revisit townhomes. Another may choose a smaller condo or a different neighbourhood.
There can also be opportunities to negotiate when sellers face fewer competing buyers. But a reduction in purchase price needs to be weighed against financing costs and the condition of the property.
Before you make an offer, make sure you know what the home will cost you to own.
Ask your mortgage professional to update your approval and explain any rate hold. Then we can compare properties, recent sales, and negotiating opportunities within a budget that works.
For sellers, buyers’ budgets matter more than yesterday’s expectations
A buyer can love your home and still be unable to finance it at your asking price.
That is why a change in borrowing costs deserves attention, particularly if your property is already on the market or you are planning to list soon.
It does not mean every seller should immediately reduce their price. The right response depends on the competition, recent sales, showing activity, and the feedback your property is receiving.
My approach is to examine where your home sits among the choices buyers can afford today.
Are competing homes offering more space or better condition? Are buyers factoring in renovation costs? Is your presentation giving them a clear reason to book a showing?
If you are thinking of selling, reviewing the strategy now gives you time to act deliberately.
Waiting may be sensible in some situations. In others, the carrying costs and uncertainty may outweigh the potential benefit. We should compare those options using your circumstances.
If you are buying and selling, look at the gap between the two
A softer selling price can feel discouraging. But if the home you want to purchase has also become more negotiable, your overall move may still work.
The important calculation includes what you receive from your sale, what you pay for your next property, transaction costs, and the mortgage you need afterward.
Looking at only one side can lead to the wrong conclusion.
This is where a coordinated sale and purchase strategy can make a meaningful difference.
For homeowners renewing, the impact depends on your mortgage
An existing fixed mortgage generally keeps its contracted rate until the term ends. Variable mortgages are typically linked to lender prime rates, with the effect on payments depending on the mortgage structure.
New fixed-rate offers are influenced by bond markets and funding costs, so they can move between Bank of Canada announcements. (rbcroyalbank.com)
If renewal is approaching, start the conversation early. Ask your mortgage professional to compare payments, terms, flexibility, and any costs associated with changing lenders or mortgage products.
For investors, test the deal under more than one scenario
Higher financing costs can put pressure on cash flow and reduce the room for unexpected expenses.
For a rental property, commercial purchase, or development site, I would want to understand how the investment performs if financing stays expensive longer than expected.
Consider vacancy, repairs, operating costs, approval timelines, and the cash required to carry the property. A project that depends on rates falling quickly deserves closer examination.
My experience as a builder and developer helps bring those practical questions into the property discussion.
What comes next?
The Bank has signalled that further increases may be needed. It has not committed to a fixed schedule.
Inflation, employment, economic growth, and global developments will help shape its next decisions. (bankofcanada.ca; full statement text reproduced by BNN Bloomberg)
For Greater Vancouver real estate, my focus is on how those changes affect actual transactions, buyers’ budgets, sellers’ competition, financing conditions, and the terms people are willing to accept.
What does this mean for your property?
That is the conversation worth having.
You may be wondering whether to list before your mortgage renews, whether your next purchase is becoming more affordable, or whether an investment still makes sense.
I have been selling real estate since 2007. Alongside my negotiation, marketing, building, and development experience, I bring a practical approach to helping clients work through those decisions.
Reach out and tell me what you are considering. We can review your property, the alternatives, and what would need to happen for your next move to work.
Imran Ali Personal Real Estate Corporation
The Ali Group | eXp Realty
604-616-5553 | [email protected]
TheAliGroup.ca
Market information as of October 30, 2026. Mortgage advice and qualification should be confirmed with your lender or mortgage broker.
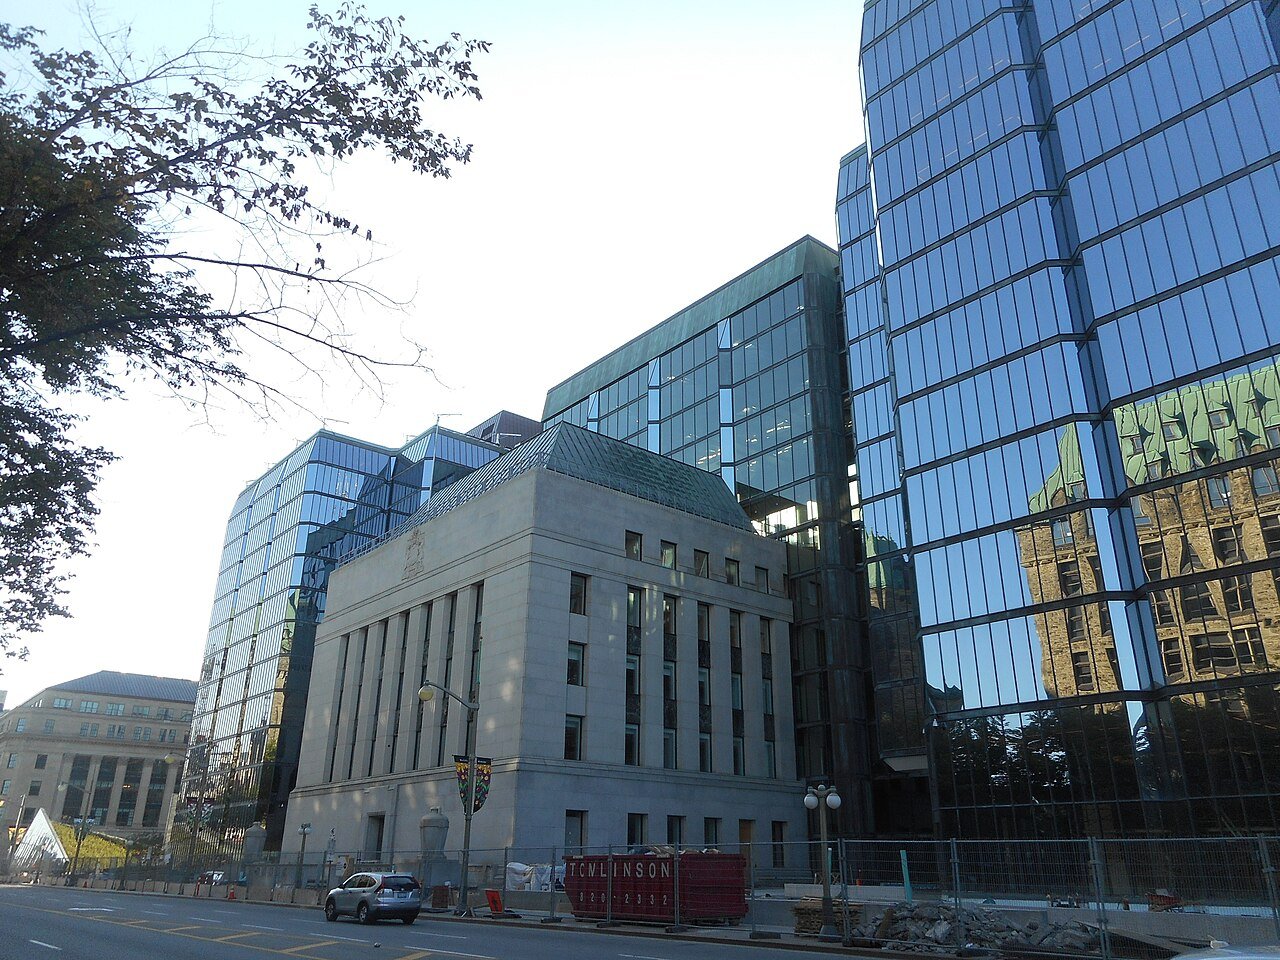
Photo: “Siège de la Banque du Canada - 01” by Jeangagnon, via Wikimedia Commons, licensed under CC BY-SA 4.0. Changes made: cropped and darkened for display. The adapted image is shared under the same licence.